News
EXPLAINER: What You Need To Know About 4th Extension Of 2025 Budget

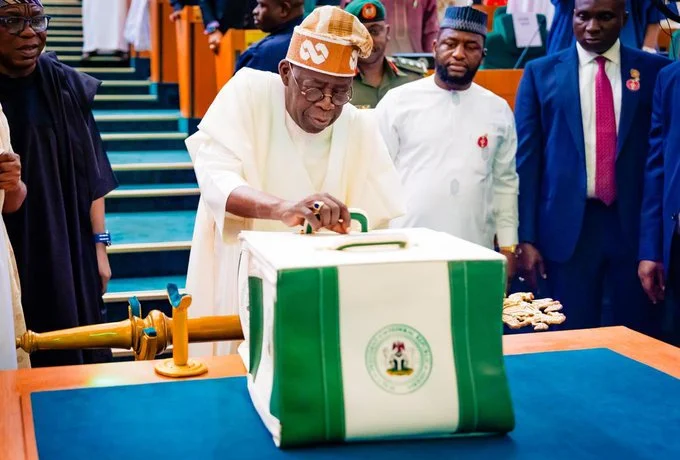
Nigeria’s 2025 capital budget has entered another extension period, allowing the Federal Government to continue implementing projects captured in the 2025 Appropriation Act beyond the original deadline and into 2026.
The development has raised fresh legal, fiscal and accountability concerns among lawyers and civil society actors, particularly over the implications of having the extended 2025 capital budget operate alongside the 2026 Appropriation Act and preparations for the 2027 budget.
The debate centres on how long an annual appropriation can be extended, how expenditure should be tracked across overlapping fiscal years, what happens to unspent funds and whether repeated extensions could weaken legislative oversight of public finances.
Here is what you need to know about the fourth extension.
What is the fourth extension about?
The extension concerns the capital component of the 2025 Appropriation Act.
The National Assembly recently extended the deadline for implementing the 2025 capital budget from June 30 to September 30, 2026, after lawmakers said several projects captured in the budget remained incomplete.
The extension provides additional time for implementing agencies to execute projects and spend funds already authorised under the relevant appropriation.
However, the latest extension has attracted attention because it takes place while the 2026 budget is already in operation and discussions around the 2027 fiscal year are approaching.
This means expenditure authorised under the 2025 budget can continue into a period in which another annual appropriation is already being implemented.
That overlap is at the heart of the concerns raised by the lawyers, the Nigerian Economic Summit Group and Accountability Lab Nigeria.
What does the Constitution say about annual budgets?
Section 81(1) of the 1999 Constitution requires the President to cause to be prepared and laid before the National Assembly estimates of the revenues and expenditure of the Federation for the “next following financial year.”
Section 318 defines a financial year as a period of 12 months beginning on January 1 and ending on December 31.
The Nigerian Economic Summit Group notes that Nigeria’s public finance system is based on annual budgeting, with the process anchored in Chapter V, Part I of the Constitution.
Under the framework, the President prepares and presents an Appropriation Bill to the National Assembly, which considers and approves expenditure.
The Appropriation Act then authorises expenditure from the Consolidated Revenue Fund for the relevant financial year.
The Financial Year Act standardises the financial year as running from January 1 to December 31.
The issue arising from the repeated extensions is therefore whether prolonged implementation of an earlier appropriation is consistent with the principles of an annual budget cycle and, more importantly, whether the expenditure remains clearly identifiable and auditable.
Why has Nigeria continued to extend budgets?
One of the explanations offered by the experts is that delays occur at different stages of the budget process.
These include delays in preparing the budget, presenting it to the National Assembly, passing it and obtaining presidential assent, as well as delays in implementing approved projects.
Where projects remain incomplete at the end of the approved implementation period, the legislature may extend the period to allow government agencies to complete them.
However, repeated extensions have raised concerns that what should be an exceptional mechanism could become a recurring feature of Nigeria’s budget process.
Lawyers react
Human rights lawyer, Udochukwu Onoh, said the recurring extensions reflect deeper weaknesses in Nigeria’s budget process, particularly delays in the approval and presidential assent of appropriation bills.
“Every budget is intended to be expended within the same year. Unfortunately, in Nigeria, it takes us longer to deliberate on budget approval and presidential assent,” Onoh said.
According to him, delays in signing appropriation bills can push budget implementation into subsequent fiscal years and create overlapping budget cycles.
“Even when it has been passed, the signing by the President takes time to the extent that it has to spill over to the next year. This is a serious problem and citizens should hold the office holders accountable,” he said.
Onoh also raised concerns about the treatment of unspent appropriations, arguing that government agencies must properly account for funds before another budget cycle takes effect.
“The fact that whatever is not expended is not retired is another problem. Even CSOs that should hold power to account are gradually losing their voices,” he said.
He said agencies should ensure that expenditure is properly retired and accounted for where implementation extends into another fiscal year.
“If the budget is yet to be implemented, by virtue of the fact that the existing one is in use, then the agencies should make necessary retirement before the next one. Every penny should be accounted for,” Onoh said.
He acknowledged that some extensions could result from circumstances beyond the control of implementing agencies but said this should not weaken accountability.
“The extension could be for reasons beyond their control, but the money involved should not develop wings and fly; otherwise, there is a serious problem and the citizens must stand up to their responsibility to hold power to account,” he said.
Another lawyer, Victoria Adaji focused on the constitutional and public finance implications of repeatedly extending the 2025 capital budget.
She said the concerns become more pronounced because the extended 2025 budget operates alongside the signed 2026 Appropriation Act, while discussions on the 2027 fiscal year are approaching.
Adaji said Section 81(1) of the Constitution, which refers to the “next following financial year”, should be considered alongside Section 318, which defines the financial year as running from January 1 to December 31.
“The legal implications of the National Assembly extending the 2025 budget’s capital component for a fourth time to December 31, 2026, while overlapping with a signed 2026 budget and staring down 2027 fiscal discussions, represent a structural breakdown in Nigeria’s public finance management,” Adaji said.
She said the overlap could make it difficult to establish which appropriation authorised particular expenditure, especially where projects continue across different budget years.
“This poses a tracking nightmare as this violates basic public accounting laws,” she said.
Adaji said the situation could also create difficulties for the Auditor-General for the Federation in determining the budgetary authority behind expenditure incurred during the overlap.
“The Auditor-General of the Federation faces a legal gridlock trying to track whether a contract executed in October 2026 was funded by the 2025 extension or the 2026 main allocation,” she said.
She said repeated extensions could effectively transform the annual budget framework into one where different fiscal years operate simultaneously.
“By this four-time extension, Nigeria is effectively transforming its budgetary framework into a rolling three-year cycle managed through ad-hoc amendments, eroding the rule of law in public finance management,” Adaji said.
Adaji also identified the absence of a statutory deadline in the Constitution for presenting the annual budget as part of the problem.
“It’s quite unfortunate that our constitution poses no statutory deadline which is the driving force. It only defined financial year unlike Ghana,” she said.
She compared Nigeria with Ghana and Kenya, saying:
“Ghana section 179(1) requires presentation of budget document not later than one month before the end of the financial year or Kenya, section 221(1) requiring submission at least two months before the end of each financial year.”
The Nigerian Economic Summit Group provides a broader public finance perspective on the issue.
The Group in a publication on its website notes that persistent delays in budget preparation, passage and implementation have necessitated legislative extensions beyond the original statutory timelines.
According to the NESG, this raises questions around constitutional validity, fiscal discipline and governance.
The Group describes the development as contributing to “a pattern of fiscal improvisation” and the emergence of concurrent budgetary operations.
The NESG, however, recognised that extensions can serve a practical purpose.
According to the Group, extending implementation can prevent disruptions to essential services and allow government to complete delayed projects.
Its concern is with repeated extensions and their cumulative effect on the budget system.
The Group warned that frequent rollovers can weaken legislative oversight and create blurred audit trails.
It also says repeated extensions can “disincentivize timely budgeting” and diminish parliamentary control over public expenditure.
According to the NESG, “extensions diminish parliamentary power over the purse, transforming the legislature from appropriation authority to retrospective validator.”
The Group further warned that normalising repeated extensions could create a moral hazard by reducing incentives for timely budget preparation, passage and implementation.
The Country Director of Accountability Lab Nigeria, Friday Odeh, criticised the fourth extension from an accountability and expenditure-monitoring perspective.
Odeh argued that repeatedly extending the implementation period could weaken the legal force of an appropriation law.
“The fourth extension of the 2025 capital budget destroys the legal sanctity of the Appropriation Act, reducing a statutory law into a flexible administrative suggestion or political convenience,” he said.
He said overlapping spending windows across fiscal years could make expenditure tracking more difficult and obscure funds carried over from one budget cycle to another.
“Operating overlapping spending windows across multiple years creates an unmonitored dual fiscal regime that dismantles expenditure tracking, obscures rollover funds, and severely cripples the oversight capacity of the Office of the Auditor General for the Federation,” Odeh said.
He also argued that repeated extensions could conceal deeper problems with government revenue and the implementation of capital projects.
“Repeated extensions disguise chronic revenue deficits and poor capital absorptive capacity as mere procurement delays,” he said.
Odeh said that stretching implementation timelines could affect government cash-flow management, borrowing requirements and inflation.
“By continuously stretching execution timelines to cover unfunded budget lines, the executive branch distorts cash flow management, inflates debt service costs through late borrowing, and triggers inflationary pressures when pent up liquidity is suddenly released into the economy,” he said.
He also criticised the National Assembly’s handling of repeated extensions, arguing that lawmakers should exercise stronger control over public expenditure.
“The legislature has abdicated its constitutional power of the purse by granting continuous lifelines instead of enforcing fiscal realism,” Odeh said.
He proposed an immediate project-by-project audit of items covered by the extension, tighter conditions for future extensions and the re-appropriation of unfinished projects into subsequent annual budgets.
“Restoring accountability requires an immediate project by project audit of extended items, a strict single extension limit tied to performance conditions, and the systematic re-appropriation of unfinished capital works into subsequent annual budgets rather than legalizing indefinite extensions,” Odeh said.
What happens to unfinished projects?
The central practical justification for the extension is that some projects captured in the 2025 capital budget remained incomplete.
An extension gives implementing agencies additional time to execute such projects under the extended appropriation.
But the experts differ in emphasis on how unfinished projects should be handled in future.
Onoh stressed the need for proper retirement and accounting for funds already spent.
Adaji focused on ensuring that expenditure can be clearly linked to the appropriation that authorised it.
The NESG highlighted the effect of repeated extensions on legislative oversight and incentives for timely budgeting.
Odeh proposed that unfinished capital projects should be systematically re-appropriated in subsequent annual budgets rather than relying on repeated extensions.
Under such an approach, unfinished projects would be explicitly captured and authorised in a subsequent appropriation, creating a new and identifiable legislative trail for the expenditure.
Does an extension mean government can spend without appropriation?
No.
An extension does not, by itself, amount to unlimited authority to spend public funds.
The relevant question is whether expenditure during the extended period is covered by the legislative authority provided through the extension and whether the spending is properly recorded, accounted for and audited.
The concern raised by the lawyers is that overlapping appropriations can make it more difficult to establish which budget authorised a particular expenditure.
That is particularly relevant to projects that continue across fiscal years.
Why is expenditure tracking important?
Expenditure tracking enables oversight institutions and the public to determine how public funds were used, which project received the money, under which appropriation the expenditure was authorised and when the spending occurred.
Where budget years overlap, the accounting trail can become more complicated, particularly where the same project continues from one appropriation into another.
What are the wider implications?
The fourth extension has reopened a wider debate about Nigeria’s annual budgeting system.
At the centre of that debate are four interconnected issues: timely passage of budgets, timely implementation of approved projects, legislative control over public expenditure and transparent accounting of government funds.
The lawyers are particularly concerned about the constitutional and legal implications of overlapping budget years.
The NESG is concerned about the effect of repeated extensions on fiscal discipline, legislative oversight and incentives for timely budgeting.
Accountability Lab Nigeria has focused on expenditure tracking, capital absorption, borrowing and the need for stronger conditions around extensions.
Although the speakers approach the issue from different perspectives, they all point to the importance of ensuring that extended budget implementation remains subject to clear legislative authority, transparent accounting and effective oversight.
The fourth extension of the 2025 capital budget is not simply about giving government agencies more time to complete projects.
It raises fundamental questions about how Nigeria manages its annual budget, how long an appropriation should remain operational, how overlapping fiscal years should be accounted for and how the legislature and audit institutions can effectively track public expenditure.
While an extension can provide additional time to complete delayed projects, repeated extensions have prompted concerns about fiscal discipline, legislative oversight and the clarity of expenditure records.
The central challenge is therefore to ensure that the additional implementation period does not weaken the principles of annual appropriation, transparency and accountability that underpin Nigeria’s public finance system. (Daily trust)
-

 News7 hours ago
Court Orders Wike’s Son Jordan to Produce American Passport in $2.1m Abuja Land Suit
-
News7 hours ago
NEMA deploys rescue teams as floods ravage states
-
Politics6 hours ago
Pantami wins PDP repeat governorship primary in Gombe
-
News6 hours ago
After 68 Days Vacation, Lawmakers Embark On Another Recess
-
Metro7 hours ago
Lagos teen detained over slippers freed after four years
-
Politics6 hours ago
2027: Which running mate brings the most votes – Shettima, Amaechi or Kwankwaso?
-
News7 hours ago
Mixed reactions as FG demarcates First Niger Bridge
-
Sports7 hours ago
AFCON Qualifier: Guinea-Bissau Humble Super Eagles 3-0