Business
Folawiyo’s T1 Marine battles revenue authority over $1.2m tax demand

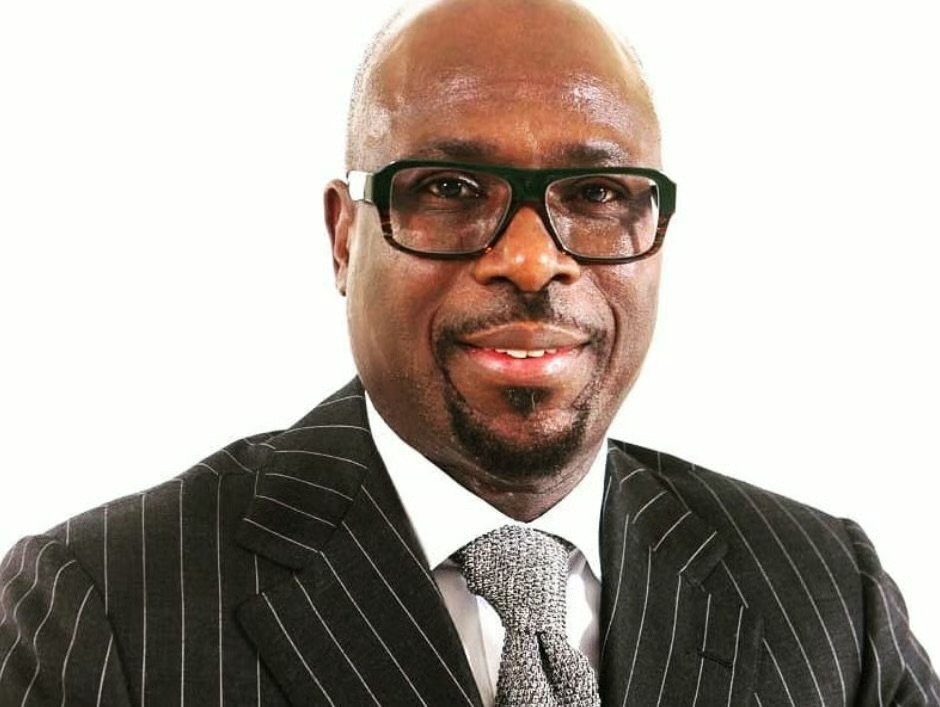
T1 Marine Services Limited (TMSL), chaired by billionaire businessman Tunde Folawiyo, is locked in a protracted legal battle with the Nigerian tax authority over tax demands totalling ₦1.65bn (about $1.2m). T1 Marine, registered in 2012, provides marine support services to oil and gas companies operating in Nigeria.
Folawiyo is the managing director of the Yinka Folawiyo Group, a business conglomerate founded by his late father, Wahab Folawiyo, with interests in oil and gas, agriculture, shipping and real estate.
The company is challenging what it describes as the erroneous calculation of its Tertiary Education Tax (TET), Companies Income Tax (CIT), Withholding Tax (WHT) and Value Added Tax (VAT) obligations for the 2014, 2015 and 2016 financial years, totalling ₦1,651,614,383.
It rejects the demand for ₦48,931,546 in TET; ₦893,521,679 in CIT; ₦263,634,890 in WHT; and ₦445,526,268 in VAT.
Dispute over deductible expenses
At the heart of the dispute is the Nigeria Revenue Service’s (NRS) decision to disallow ₦2.88bn in expenses that T1 Marine says were incurred in generating revenue and should therefore be tax-deductible.
One of the major issues concerns the cost of hiring vessels. T1 Marine said it did not own vessels but chartered them to fulfil its contractual obligations to oil and gas operators.
“The expenses for hiring vessels are a critical expense component for TMSL – no vessel, no work,” the firm said in its court filings. “The expenses were incurred on the lease of vessels by the appellant from a lessor resident in the Netherlands. Therefore, the expenses are tax-deductible, as they were incurred for the purpose of generating profits for the business in the relevant years.”
The company said the NRS audit team had, in previous years, treated the expenses as an allowable deduction. “There is therefore no justification for the decision by the respondent to disallow them now,” it said.
Another point of disagreement concerns administrative expenses, particularly the school fees paid for the children of expatriate employees. T1 Marine maintained that these payments formed part of its employees’ remuneration and should be recognised as deductible staff costs.
“Such staff costs are clearly tax-deductible under the tax laws,” it said. “Therefore, there is no legal basis for the refusal of the respondent to treat them as an allowable expense.”
Furthermore, the firm said the tax authorities also wrongly disregarded the sums of ₦48.8m and ₦43.8m, paid by Anchorsafe Limited on its behalf in 2014 and 2015, respectively, to provide seafarers to man TMSL vessels in Nigeria.
“Based on the manning agreement with Anchorsafe, the appellant (TMSL) is expected to reimburse Anchorsafe for all costs incurred in relation to its services, including overheads,” it stated.
VAT and withholding tax calculations contested
Beyond the disputed business expenses, T1 Marine accused the NRS of miscalculating its VAT and WHT liabilities by relying heavily on its financial statements without adequately considering the nature of its transactions and the supporting records.
“By solely relying on financial statements in arriving at its assessment, the respondent failed to consider tax-exempt items and items that have already been subject to tax, such as bond fees and sundry items purchased using cash,” it said.
The firm said the tax authorities erred in law when they assessed the firm’s VAT at ₦445,526,268 for 2014-2016 by including tax-exempt transactions, including those in a Free Trade Zone. TMSL also rejected the additional ₦263,634,890 in WHT demanded by the NRS for 2014-2016. It also opposed the NRS’s demand for interest and penalties on its alleged outstanding VAT and WHT for 2014-2016.
“The appellant has not admitted liability for the alleged VAT and Withholding Tax liabilities and has taken steps to challenge the liabilities,” it said.
TMSL urged the tax tribunal to quash the 12 notices of demand issued to it by the NRS in respect of TET, CIT, WHT and VAT for the years 2014, 2015 and 2016.
NRS defends tax assessments
However, in its reply filed in February 2023, the NRS maintained that the tax assessments were correct and that it had acted lawfully in issuing them. It disputed TMSL’s claim that it incurred costs in hiring vessels for its operations.
The NRS said the assessments followed a reconciliation meeting at which documents and bank statements were received and reviewed, after the tribunal had earlier directed both parties to seek an amicable resolution of the dispute.
Regarding the school fees paid for expatriate employees’ children, the tax authority argued that although T1 Marine provided third-party documents showing the payments, it failed to produce the employees’ employment contracts establishing that the company was contractually responsible for those expenses. “Hence, the expense was correctly disallowed,” it stated.
The NRS also challenged T1 Marine’s account of the payments to Anchorsafe, arguing that the manning agreement presented to it did not establish that Anchorsafe had incurred the expenses on T1 Marine’s behalf with the understanding that it would be reimbursed.
“The appellant’s ledger also did not show any reimbursed expenses paid to Anchorsafe by the appellant in respect of the alleged tax-exempt items,” it said. The revenue service also defended its decision to charge interest and penalties on the alleged outstanding VAT and WHT.
Citing the applicable tax provisions, the authority argued that a taxable entity that fails to remit taxes within 30 days of the due date commits an offence and, upon conviction, is liable to pay the outstanding tax, together with a penalty of 100% of the unremitted amount.
The NRS urged the tribunal to declare TMSL indebted to the government and liable to remit ₦893,521,679 in CIT, ₦48,931,546 in TET, ₦445,526,268 in VAT, and ₦263,634,890 in WHT.
The dispute, dating back to 2019 and now in its eighth year, last came before the Tax Appeal Tribunal in Lagos for hearing on 3 November 2026. (The africa report)
-

 African News11 hours ago
Fani-Kayode’s confession to being cured of madness circulates across South Africa
-
World News23 hours ago
US proposed ceding Ukraine territory in exchange for joining NATO
-
Politics23 hours ago
ADC: Atiku hasn’t reached out to me despite coming from the same zone – Nafiu Bala
-
Metro23 hours ago
Zainab, Kwankwaso’s daughter, files for divorce from Gov Yusuf, offers to return dowry
-
Politics7 hours ago
Tinubu, Aregbesola met three times despite rift – APC chieftain, Prof Adeyeye
-
News23 hours ago
Clashes between gangs, vigilantes kill over 50 in Zamfara – Report
-
Opinion10 hours ago
Why Nigerians vote the way they do
-
African News6 hours ago
Nigeria’s mission in S/Africa urges calm in row over Ramaphosa spokesman’s remarks