Business
Shell, Esso and Agip test Tinubu’s new tax regime in court

Three international oil companies, along with the Nigerian National Petroleum Company Limited (NNPC), have objected to a move by Nigeria’s revenue authority to retroactively apply the country’s new tax regime.
The IOCs are challenging the Nigerian Revenue Service’s (NRS) demand for $19,598,176 as a Development Levy on profits from their operations under Oil Mining Lease (OML) 118 in the Niger Delta last year.
The Development Levy is a new tax introduced by Nigeria last year, following President Bola Tinubu’s ambitious tax reforms, which saw the sweeping overhaul of the country’s decades-old tax regime.
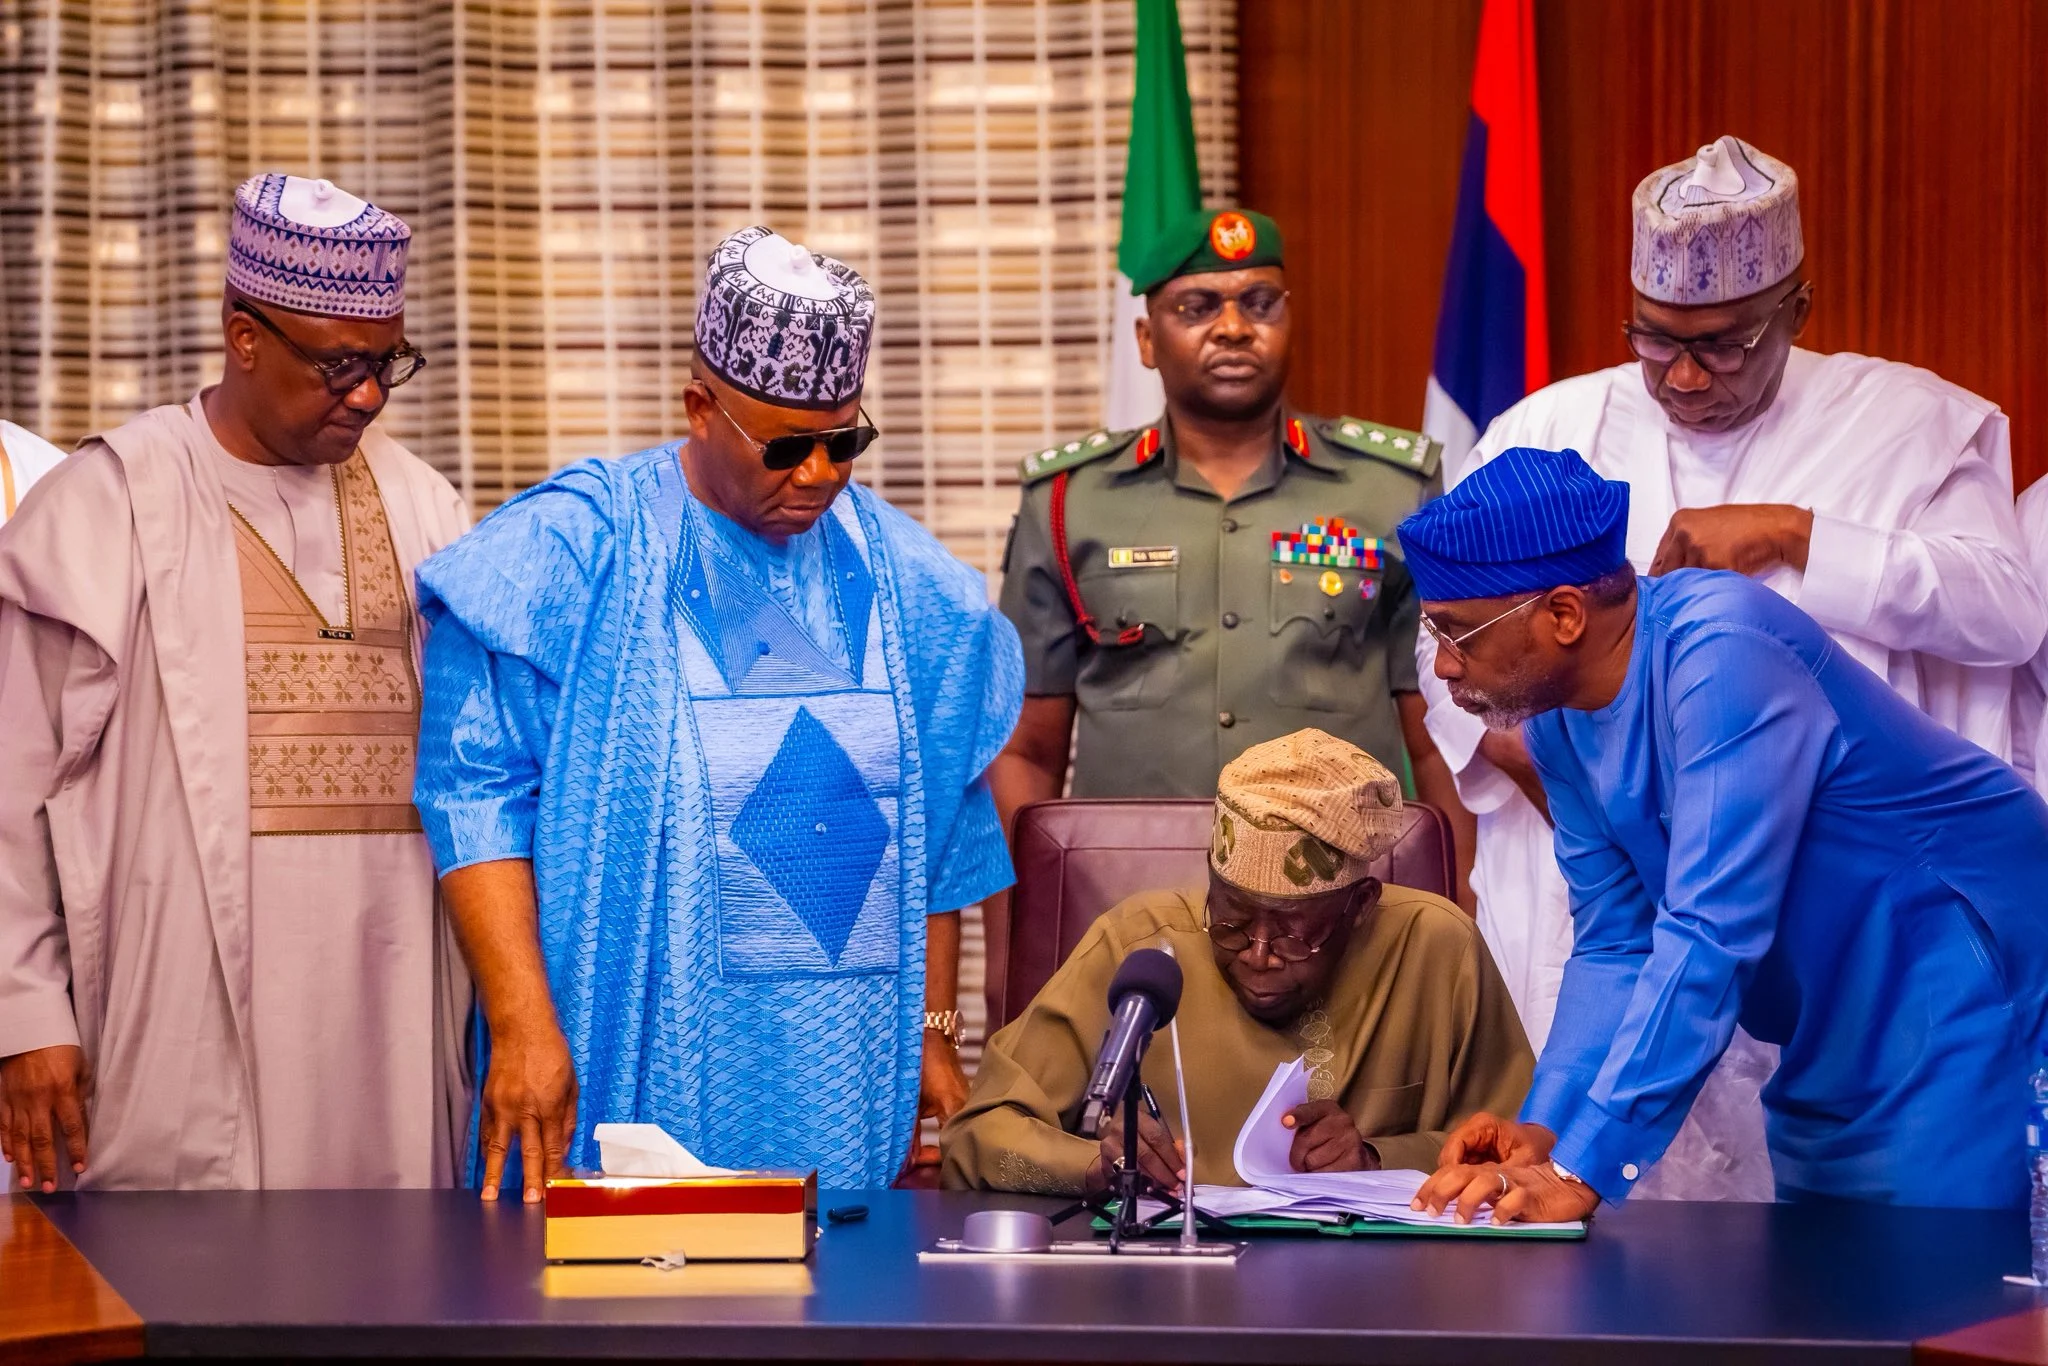
After months of heated legislative debates and political negotiations, the National Assembly passed four new tax laws proposed by Tinubu last year. The president signed the four laws in June 2025 but said their implementation would be delayed until 1 January 2026.
The new tax legislation comprises the Nigeria Tax Act (NTA), the Nigeria Tax Administration Act (NTAA), the Nigeria Revenue Service (Establishment) Act (NRSA) and the Joint Revenue Board (Establishment) Act (JRBA).
In rejecting the $19.5m Development Levy, the IOCs argue that the new tax laws, although signed by the president in June 2025, did not take effect until 1 January 2026 and therefore cannot apply to profits earned in the previous accounting year.
SNEPCo, EEPNL and NAE challenge NRS’s demand
The three oil companies involved in the dispute are Shell Nigeria Exploration and Production Company Limited (SNEPCo), Esso Exploration and Production Nigeria Limited (EEPNL) and Nigerian Agip Exploration Limited (NAE).
Under Section 59 of the NTA, the Development Levy is charged at 4% of a company’s assessable profits and applies to companies with annual gross turnover exceeding N100m ($74,289).
The levy consolidates four previously separate charges: the Tertiary Education Tax (TET), previously set at 3% of assessable profits; the National Information Technology Development Agency (NITDA) Levy, at 1%; the National Agency for Science and Engineering Infrastructure (NASENI) Levy, at 0.25%; and the Police Trust Fund (PTF) Levy, at 0.005%.
In their court filings, the companies said the NRS wrote to them on 10 July 2026, demanding $19,598,176 in Development Levy for their 2025 operations, citing the provisions of the new NTA.
They are contesting the demand on the basis that the law cannot be applied retrospectively to an accounting period that ended before the law’s commencement.
“Neither the NTA nor any other applicable law authorises the retroactive application of Section 59 to an accounting period that ended before the NTA commenced,” they said.
The companies also cited transition guidelines issued by the finance minister, Taiwo Oyedele, on 18 June 2025, which they said expressly provided that the new tax regime would take effect on 1 January 2026.
“The Transition Guidelines specifically provide that profits for accounting periods ending before the commencement of the NTA shall be based on the repealed/amended laws, and that only accounting periods ending after 1 January 2026 shall be subject to Development Levy under the NTA,” the IOCs said.
The IOCs further argued that they had already met their tax obligations for the 2025 accounting period under the previous regime.
They said they had calculated and paid $61,118,229, representing 3% of their assessable profits from OML 118 operations, as Tertiary Education Tax (TET).
They therefore consider the NRS’s additional demand of $19.5m unjustified, arguing that it amounts to an attempt to impose the new 4% Development Levy prematurely by demanding an extra 1% of their assessable profits.
“The Transition Guidelines confirm that the Development Levy introduced by Section 59 of the NTA does not apply to profits arising in the 2025 accounting period,” they said, asking the court to set aside the demand.
First major test of Tinubu’s tax reforms?
However, the NRS maintains that its demand is lawful and has refused to withdraw the assessment, prompting the oil companies and the NNPC to seek judicial intervention.
The suit could become an early legal test of the Tinubu administration’s tax reforms, particularly the interpretation of transitional provisions governing the shift from the old to the new tax framework.
The outcome could have implications beyond the three oil companies, especially for businesses whose accounting periods straddle the transition to the new regime.
The reforms are part of Tinubu’s broader ambition to expand government revenue and reduce Nigeria’s dependence on borrowing. Three months after taking office in 2023, the president announced a target to double the country’s tax-to-GDP ratio from 9.4% to 18% by 2026.
The four new laws were designed to simplify tax administration, consolidate multiple levies and improve revenue collection. However, the dispute over the Development Levy highlights the legal questions that may arise as businesses and tax authorities navigate the transition to the new framework. (The Africa Report)
-

 Politics14 hours ago
2027: INEC dispatches 186,277 BVAS to states
-
News14 hours ago
Senate sends State Police Bill to Tinubu for assent
-
Sports14 hours ago
FIFA Appoints Amokachi, Four Others To Manage Nigeria Football Federation
-
Metro14 hours ago
Eight-hour gridlock paralyses Lagos-Ibadan Expressway
-
Politics14 hours ago
Tinubu Revises Campaign Schedule, Drops Bauchi, Adds More States
-
Metro14 hours ago
Kano TikToker Jailed For ‘Insulting’ Hisbah DG
-
Business14 hours ago
Chairman’s firm buys 9.125% of Seplat senior notes
-
News14 hours ago
US hails Nigerian military over rescue of 125 kidnap victims